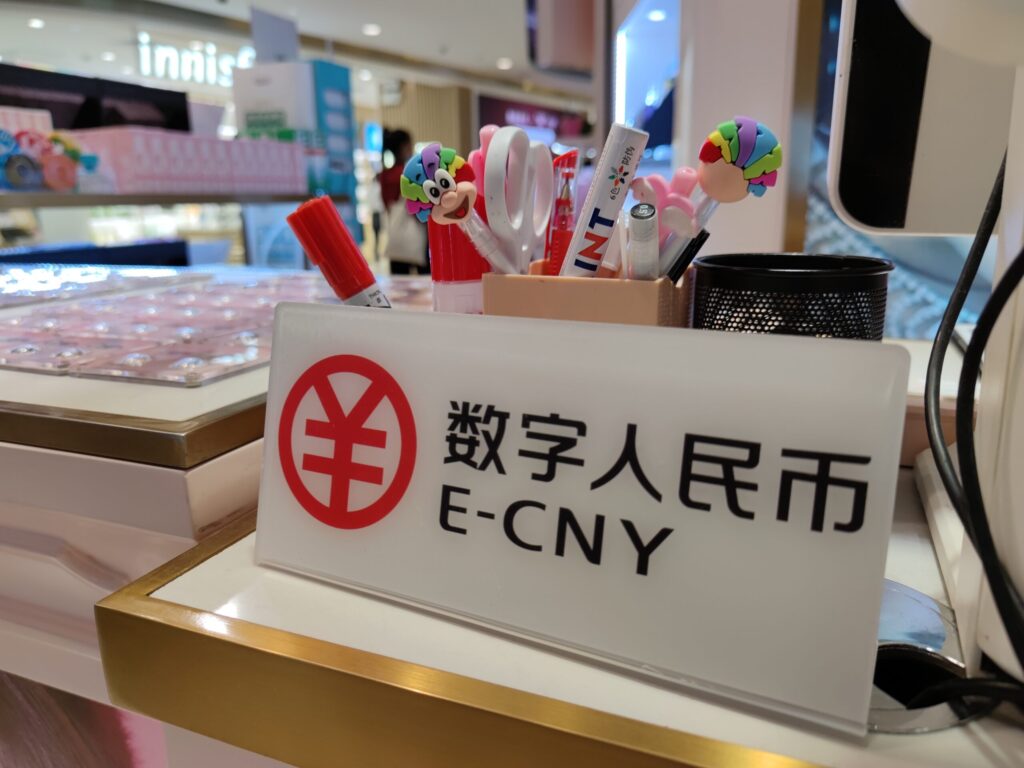
Ten months ago, I explained how China was preparing its digital yuan (e-CNY) for prime time. Since then, Beijing has been busy at work expanding its global payments network. For example, the People’s Bank of China (PBOC), alongside other Chinese financial authorities, has rebuilt the e-CNY’s legal and technical foundations. But beyond the digital yuan, they launched a second cross-border platform alongside Project mBridge, and they widened the reach of the Cross-Border Interbank Payment System (CIPS). These developments suggest that Beijing is building not one but multiple interconnected layers of financial infrastructure to engage its partners to varying degrees. Here is what has changed since January:
At home, China rebuilds the digital yuan
On January 1, the PBOC implemented a new management framework requiring commercial banks to pay interest on verified e-CNY wallet balances at the same rate they pay demand deposit accounts (such as checking accounts). Officials argued that this would start a shift from the pursuit of “digital cash” toward deeper integration with the regulated financial system. At roughly 0.05 percent, the interest offers little financial incentive to households. But for commercial banks, this means that they can now treat e-CNY held in wallets as a deposit liability that they manage on their own balance sheets, which gives them a stronger incentive to promote the digital yuan’s adoption. The PBOC has since tripled the number of e-CNY operating banks to thirty, which for the first time includes city commercial banks.
Adoption for the retail e-CNY has been weak. That’s the case even though nearly 230 million personal wallets have been opened, according to the PBOC. One of the factors limiting its adoption among individuals is competition from private payment companies such as Alipay and WeChat Pay. To be sure, by the end of September, all-time e-CNY transactions reached about 31 trillion renminbi (roughly $4.6 trillion), which is double the figure recorded ten months earlier. But in September, transaction value rose 123 percent year on year, while the number of transactions rose just 12 percent. The gap is most likely related to growth from large-business and public-sector payments rather than everyday retail payments.
The debate about whether the digital yuan is a central bank digital currency (CBDC) is still open, as our CBDC tracker notes. A CBDC is a liability of the central bank, whereas the e-CNY was originally designed as a digital substitute for cash. A draft finance law published in March still treats it that way. But the January changes point in the other direction. Retail e-CNY balances now sit on commercial banks’ balance sheets, earn interest, and are covered by deposit insurance. That makes them appear less like digital cash and more like what the PBOC now calls “digital deposit money.”
Whichever way the debate ends, the PBOC will remain deeply involved in the project. As Deputy Governor Lu Lei put it, the central bank plays a role in providing technical support and supervision with help from the e-CNY Operations and Management Center in Beijing. In October, Lu unveiled a central bank–side system, the Digital Currency & Electronic Payment System (DCEPS), which gathers e-CNY issuance, retail and wholesale payments, and smart contracts onto one platform. Officials say it will cut integration and liquidity-management costs for banks. In effect, the PBOC is stepping back from holding retail balances but will still maintain control of the rails they run on.
Beijing’s long-term commitment to the e-CNY project remains unchanged. The PBOC’s latest five-year plan, released in August, commits to developing the digital yuan “steadily,” consistent with the fifteenth five-year plan.
Abroad, China diversifies its digital payment options…
The central banks behind Project mBridge are continuing to push forward on a cross-border wholesale CBDC, with the PBOC playing a leading role. However, Saudi Arabia’s central bank, which joined in June 2024, left the project after completing its proof of concept in May 2025; the departure was reported over a year later. Saudi Arabia’s decision could hurt mBridge’s commodity-trade ambitions, given the country’s weight as an oil exporter.
Meanwhile, mBridge added two members in June: Macau and Mongolia. On the first day, three Macau banks completed twenty-three transactions worth nearly $161 million, settling trade and remittances with mainland China, Hong Kong, and the United Arab Emirates. Lu spoke in Macau in June, saying he hoped its entry would also help link the planned digital pataca to China’s bilateral cross-border e-CNY platform.
That PBOC cross-border project Lu mentioned is one that Washington has largely ignored. Cross-border e-CNY Transfer Services (CBETS) is the cross-border counterpart to DCEPS. It shifts the PBOC’s focus from e-CNY used abroad mostly by tourists to e-CNY settlements between banks for trade and remittances. On June 16, twenty-six institutions, including Standard Chartered China and overseas branches of Chinese banks, signed on as the project’s first direct participants, covering eight jurisdictions from Hong Kong to Brazil.
Unlike mBridge’s shared ledger, CBETS connects China’s e-CNY system to each partner’s conventional or digital payment systems one jurisdiction at a time, and lets banks there plug in directly. It settles e-CNY transfers between them around the clock. Early applications have centered on commercial trade settlements. An importer based in Xiamen, China, used e-CNY to pay for Malaysian durian, reducing settlement time to just thirty minutes, while China Southern Power Grid received e-CNY payments for electricity exports to Laos, cutting settlement times from three working days to less than five hours. Beijing hopes that by accelerating cross-border payments with CBETS, it can encourage greater international use of the renminbi and reduce reliance on dollar-based payment infrastructure. But it is unclear how much international demand there actually is for the digital yuan—or what foreign recipients would do with it once they receive it. Together, Project mBridge and CBETS give partners flexibility. For some countries, a bilateral connection through CBETS may be politically easier than joining a multilateral platform such as mBridge, which has become a geopolitical issue.
… and widens the CIPS network
China’s most important project perhaps remains CIPS. At the Financial Street Forum in Beijing in October, PBOC Governor Pan Gongsheng made a pointed claim about the renminbi’s global reach. According to SWIFT data, the renminbi accounts for 3 to 4 percent of international payments, ranking fifth among currencies. But factor in settlements through CIPS and banks’ internal systems, the governor argued, and its share rises to 6 to 7 percent, placing it third.
CIPS is a renminbi messaging and settlement platform that China launched in 2015. From January through October, it processed 7.7 million transactions worth 182.8 trillion renminbi (roughly $27 trillion), already surpassing its total for all of 2025. October alone accounted for 807,000 transactions worth 20.5 trillion renminbi (roughly $3.1 trillion). As of the end of September, CIPS had 214 direct participants and 1,651 indirect participants across 133 countries and regions.
Over the past two years, the operator of CIPS has broadened its network beyond the overseas affiliates of Chinese banks to include foreign commercial banks, connecting them directly to the system. In July, CIPS Co. signed a formal memorandum of cooperation with Hong Kong Exchanges and Clearing to link up more closely with Hong Kong’s offshore capital markets, broadening CIPS’s role from trade payments to cross-border stock and bond settlement. Then in September, eleven foreign banks signed onto CIPS as direct participants, extending direct access to countries including Rwanda, Turkey, and Uzbekistan for the first time. In October, Ecobank, which operates across thirty-four African markets, also agreed to join. This expansion matters because direct participants can process payment messages within the CIPS network without relying on SWIFT for messaging, reducing US visibility into renminbi-based transactions.
CIPS transactions remain far smaller than those conducted on SWIFT and the broader Western financial infrastructure. However, China has demonstrated an ability to leverage CIPS during a crisis. After the Iran war began in late February, Tehran started controlling traffic through the Strait of Hormuz, reportedly charging some vessel fees to be settled in renminbi. China, which buys more than 80 percent of Iran’s seaborne oil, has also increasingly settled those purchases in renminbi to limit exposure to US financial oversight. For anyone paying Iran under these conditions, renminbi settlement through Chinese banks offered a way to keep trade moving outside dollar channels. CIPS transaction volumes surged in March as these disruptions unfolded. The data do not show how much of that increase was tied to Iran, but the surge underscores the value that alternative payment networks can offer countries seeking greater resilience and optionality in cross-border transactions. Capital flight may have contributed to the initial surge in March, but the fact that settlement volumes remain 50 percent above pre-March levels, combined with the onboarding of additional banks, suggests a more significant long-term shift toward sustained CIPS usage.
What to watch in 2027
It is worth watching if these initiatives expand next year—and if so, how. The PBOC has invested substantial resources in pursuing multiple pilots, seemingly testing several to see which ones gain traction. Developments to watch include whether data reveal that interest-bearing e-CNY accounts encouraged users to hold more digital yuan. Internationally, it is worth keeping an eye on whether mBridge becomes a commercial entity in Hong Kong, which jurisdictions join the platform, and whether CBETS begins publishing transaction data. For CIPS, full-year 2026 figures should offer a clearer picture of whether transaction volumes are keeping pace with expanding membership.
China’s approach does not depend on a single platform becoming a global success. Even if domestic e-CNY adoption remains limited or mBridge struggles to attract new members, CBETS and CIPS could continue to expand the reach of renminbi payments. By building multiple, overlapping networks, Beijing is giving foreign partners more ways to participate in its financial infrastructure. These efforts are unlikely to displace the dollar-based payment networks anytime soon, but over time, they will reshape the infrastructure through which international trade and payments are conducted.
Alisha Chhangani is the associate director for future of money at the Atlantic Council’s GeoEconomics Center.
Further reading
Related Reading

Image: An E-CNY payment sign is put up on a desk in a store in the Luohu District in Shenzhen city, south China's Guangdong province.